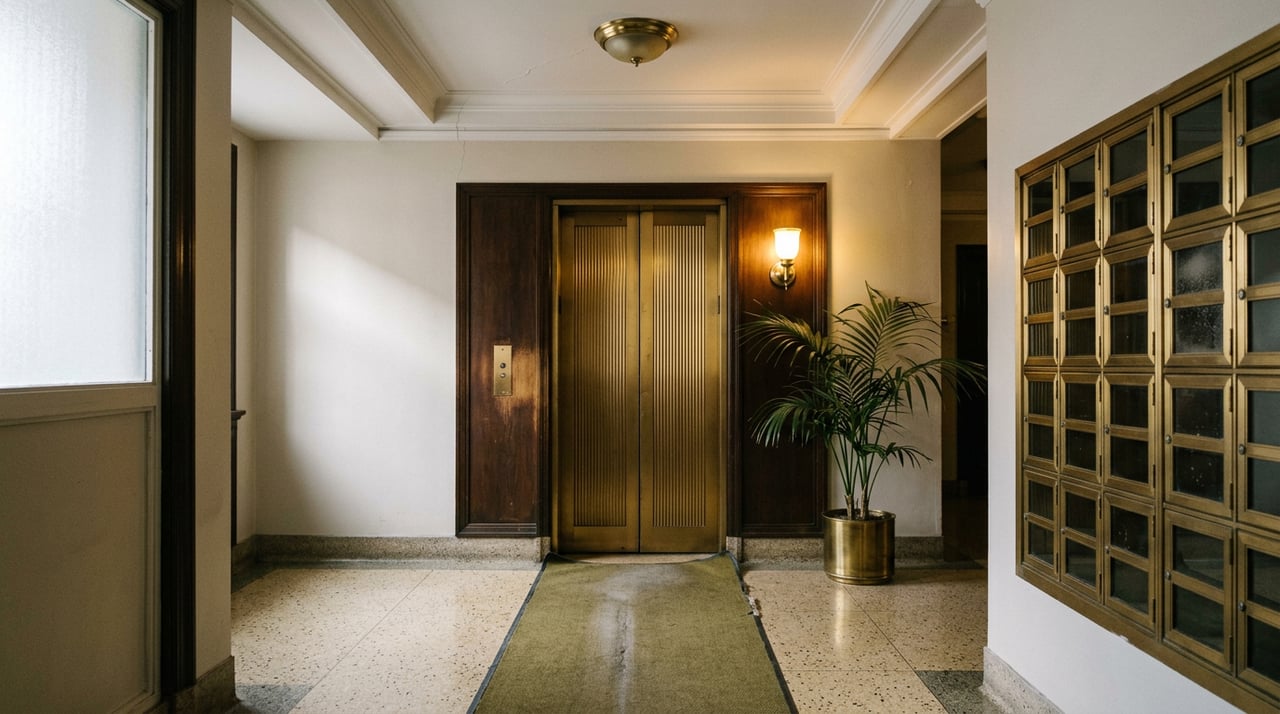
Manhattan's New Co-op Board Law Promises 45 Days. This Month, the Clock May Not Even Start.
If you are getting ready to list a Manhattan co-op this month, you have probably heard that New York City just fixed the thing everyone complains about: the board approval wait. A new law took effect on July 28, 2026, requiring co-op boards to acknowledge a buyer's application within 15 days and decide within 45. For decades, that decision could take months with no deadline at all, so this sounds like real relief.
Here is the part that hasn't made it into the headlines. The same law that sets a 45-day clock also lets a board suspend that clock for the entire period between July 1 and August 31, a stretch of 62 days that is currently underway. If your building invokes what the law calls a summer recess policy, a package submitted today could sit without a running deadline until September 1. The protection everyone is citing may not apply to the exact season you are selling in.
That gap is the real story for anyone planning a Manhattan co-op sale this fall, and it changes how you should think about timeline, pricing, and what the new law does and doesn't actually buy you.
The Cooperative Application Timeline Law (enacted as Local Law 2026/058, following City Council approval in January) governs purchase applications submitted on or after July 28, 2026. Once an application lands with the managing agent, the co-op has 15 days to confirm it's complete or spell out what's missing. Once the board treats a package as complete, it has 45 days to approve, deny, or approve with conditions. If a board misses those windows, the buyer isn't automatically approved. Instead, the city's Department of Housing Preservation and Development can issue fines starting at $1,000. Boards also get one 14-day extension as of right, and can request more time with the buyer's written consent.
The law doesn't apply everywhere. Cooperatives with fewer than 10 units, HDFC co-ops, and buildings under a government housing program like Mitchell-Lama are exempt entirely. Before you assume the timeline law protects your transaction, it's worth confirming your building is even covered.
The recess provision exists so that boards without full summer attendance aren't forced into rushed decisions during vacation months. That's a reasonable accommodation for volunteer board members. But it means a law sold as a fix for slow, unpredictable co-op timelines carries a built-in two-month pause that overlaps with a common listing season. If you list in August hoping for an October closing, and your board has adopted the recess policy, the clock on your buyer's application may not start counting until September, which pushes your realistic closing into November or later even in a best-case scenario.
For a longtime owner working through a downsizing plan, this matters less as a legal detail and more as a planning input. If you're coordinating a sale around a specific move date, a lease-up elsewhere, or a family member's schedule, don't treat the 45-day figure as a guarantee. Ask your managing agent directly whether the board has adopted a summer recess policy and build your calendar around the answer, not around the headline number.
Even outside recess season, the law changes how long a board can take to decide, not whether it says yes. Co-op boards retain the same broad discretion they've always had to reject a buyer, and they still don't have to explain a denial. That distinction matters more in 2026 than it did a few years ago, because boards across Manhattan have gotten more conservative about who they approve.
Where a debt-to-income ratio in the low 30s was routinely acceptable in 2021 and 2022, some boards are now looking for buyers in the 25 to 28 percent range. Post-closing liquidity requirements, the cash a buyer needs in reserve after the deal closes, have crept up too, with many boards now expecting one to two years of maintenance and mortgage payments sitting in liquid accounts. None of this shows up in a building's bylaws. It shows up in how a board actually behaves during review, and it's tightened alongside higher rates and more cautious lending.
For a seller, this is where the practical impact lands. The new timeline law can make a board move faster once it starts reviewing a complete package, but it does nothing to loosen the financial bar a buyer has to clear to get that approval in the first place. If your listing strategy assumes a broad, flexible buyer pool, it's worth pricing and marketing with today's tighter approval standards in mind, not the standards from a few years ago. A strong offer from a buyer who doesn't clear the board's comfort zone still ends in a rejection, deadline law or not.
Assuming your buyer does clear the board, there's a separate cost that has nothing to do with timing and everything to do with your net proceeds: the flip tax. This is a building-specific transfer fee, set out in the proprietary lease, paid to the co-op corporation rather than to any government agency. In Manhattan, 2 percent of the sale price is the most common rate, though it can run higher in some buildings and lower in others depending on the proprietary lease language.
Here's what that looks like stacked against the other costs a Manhattan co-op seller typically covers at closing:
| Cost | Typical range | Who usually pays |
|---|---|---|
| Broker commission | 5-6% of sale price | Seller |
| Combined NYC + NYS transfer tax | 1.4-2.075% of sale price | Seller |
| Flip tax (building-specific) | 1-3% of sale price, 2% most common in Manhattan | Seller, per proprietary lease |
| Attorney fees | $2,500-$5,000 flat | Seller |
On a $1.5 million sale with a 2 percent flip tax, that single line item removes $30,000 before commission or transfer taxes are even factored in. Because flip tax rates live in each building's proprietary lease rather than in any public database, the only way to know your exact number is to pull that document early, ideally before you set a list price or start planning what your net proceeds will support for your next move.
None of this means the new deadline law is meaningless. A board that used to sit on an application for four months with no consequence now has a real clock and a real penalty if it ignores that clock outside of recess season. That's a meaningful shift for buyers and sellers alike, and it should shorten the tail end of slow-moving boards once fall arrives and recess policies lapse.
The useful move for a seller right now is to separate what the law controls from what it doesn't. It controls how long a board can sit on a complete application. It doesn't control whether your building has opted into a summer recess, whether your buyer clears a tighter DTI bar than existed a few years ago, or how much your specific proprietary lease takes off the top at closing. Ask your managing agent about the recess policy before you set a listing timeline. Pull your flip tax language before you calculate net proceeds. And treat the 45-day figure as a ceiling on how long approval can drag once review actually starts, not as a promise about when your buyer's package lands on the board's desk in the first place.
Does the new law apply to every Manhattan co-op? No. Buildings with fewer than 10 units, HDFC co-ops, and cooperatives under a government housing program such as Mitchell-Lama are exempt from the timeline requirements entirely.
If my board misses its deadline, is my buyer automatically approved? No. A missed deadline doesn't approve the application. It exposes the board to a fine from the city's Department of Housing Preservation and Development, starting at $1,000, but the buyer still needs an actual board decision.
Who typically pays the flip tax, buyer or seller? In the large majority of Manhattan buildings, the seller pays, and it's deducted directly from proceeds at closing. The exact responsibility is set in each building's proprietary lease, so it's worth confirming rather than assuming.
If you're weighing a co-op sale this fall and want a clear-eyed read on your building's specific timeline, flip tax, and what a realistic closing calendar actually looks like, Binnie Sen has spent more than two decades guiding Brooklyn and Manhattan co-op owners through exactly this kind of transition. Let's Talk About Your Next Move.
Stay up to date on the latest real estate trends.
Navigate your next chapter with confidence. Whether you're downsizing, rightsizing, or helping a loved one transition, Binnie provides patient guidance, trusted expertise, and personalized support every step of the way.